
Jio Platforms Ltd. began trading in India on Oct. 28 after raising about ₹302 billion ($3.2 billion) in a fresh-share initial public offering, an issue described as the country’s largest IPO in rupee terms. The stock traded at ₹1,360 when CNBC reported on its market debut, 21.5% above the ₹1,119 issue price.
The debut put a public-market value on Reliance Industries’ telecom and digital operation at ₹12.5 trillion, or $131 billion, based on National Stock Exchange data cited by CNBC at that point in trading. The listing gives investors a separately traded route into a business spanning mobile connectivity, broadband, consumer digital services and enterprise technology, while Reliance remains its controlling shareholder.
A record measured in rupees, not every currency
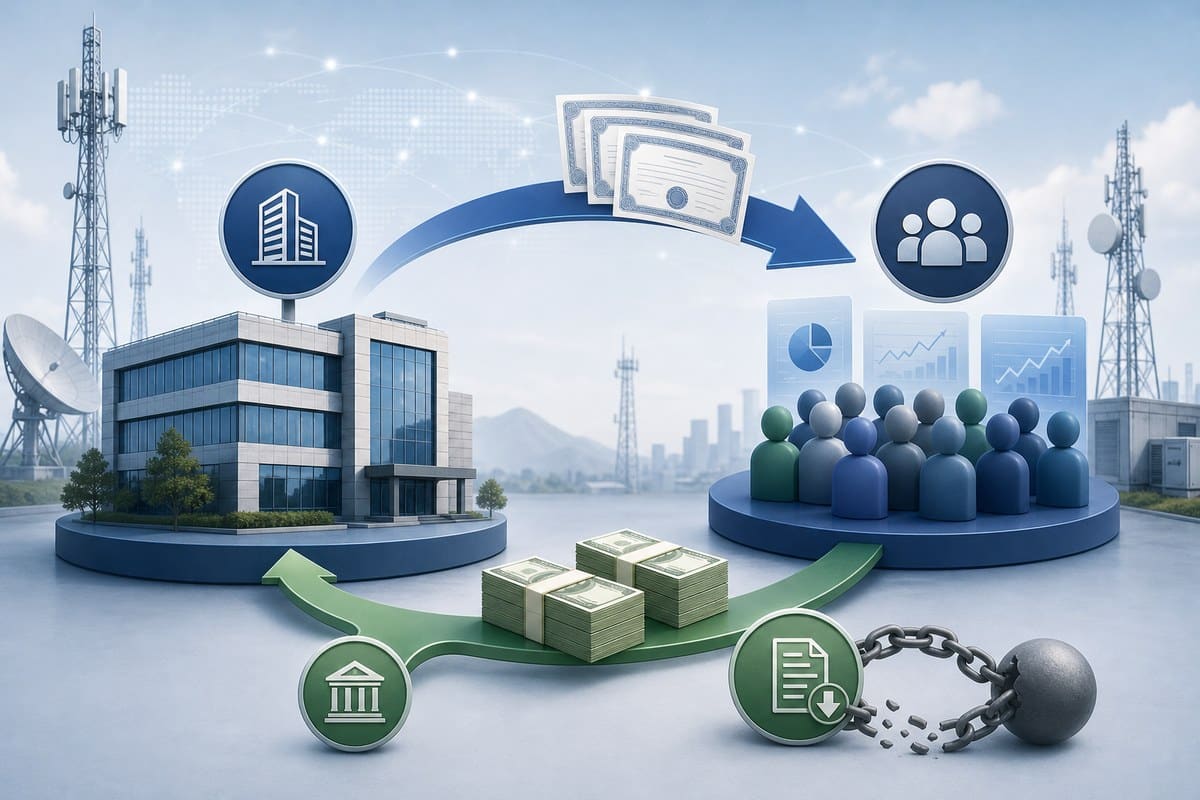
Jio sold 270 million new shares at the top of its ₹1,069-to-₹1,119 price range. Multiplying the final price by the share count produces gross proceeds of roughly ₹302.1 billion, consistent with the reported ₹302 billion total. The entire transaction was a primary issuance rather than an offer for sale, meaning the proceeds go to Jio Platforms rather than to existing shareholders selling their holdings.
The rupee qualification is important. Mint’s pre-listing account of the offering identified it as India’s largest IPO by rupee proceeds, ahead of Hyundai Motor India’s ₹278.7 billion 2024 transaction. But Hyundai’s offering was marginally larger when stated in U.S. dollars, at $3.3 billion, compared with Jio’s roughly $3.2 billion. Calling Jio the largest Indian IPO without identifying the currency measure would overstate the comparison.
The principal financial use of the new capital is also relatively specific. Mint reported that Jio intended to use up to ₹275 billion to repay or prepay certain borrowings at Reliance Jio Infocomm, its telecom subsidiary, with the remainder earmarked for general corporate purposes. That potential debt-payment allocation equals about 91% of the ₹302 billion gross proceeds, underscoring that the offering is primarily a balance-sheet transaction rather than a broad pool of expansion capital.
A JM Financial Services market update likewise described the sale as a fresh issue and cited the planned repayment or prepayment of borrowings. Neither report provides enough detail to determine the precise debt instruments, repayment schedule or any resulting interest-cost reduction.
Strong final demand followed a smaller opening-day tally
CNBC reported that the offering was subscribed more than 22 times, citing BSE figures. The qualified institutional buyer portion was subscribed 70.55 times, while the retail segment was subscribed 2.72 times. Those ratios describe applications for shares relative to the amount allotted to each investor category; they do not mean every applicant received shares or guarantee a continuing market price after listing.
The final tally also reconciles with an earlier, lower figure. JM Financial Services reported that the issue was subscribed three times as of 5 p.m. IST on Oct. 21, the first day of bidding. The public subscription period then remained open through Oct. 23, according to Mint, so the interim reading and the reported final demand are measurements from different points in the bookbuilding process rather than conflicting accounts.
Jio had raised ₹81.1 billion from anchor investors before the public issue, JM Financial Services reported. Anchor placements can establish an initial institutional shareholder base before an IPO opens to other qualified institutions, high-net-worth investors and retail buyers. The subsequent subscription data indicate that institutional demand expanded substantially during the public offering, although the available reports do not provide a full allocation breakdown by investor.
Reliance retains control alongside Meta and Google
Reliance Industries held roughly 66% of Jio Platforms before the IPO, according to shareholding data reported by CNBC and Mint. Meta held about 10% through Jaadhu Holdings, and Google International held about 7.7%. The new issuance dilutes existing investors proportionately, but the reported pre-offering ownership makes clear that Reliance’s position was large enough to preserve control after the sale.
That structure separates Jio’s new public status from a full separation from its parent. Public shareholders now have a listed security tied to Jio’s operating results, but Reliance continues to determine the group’s controlling direction. Meta and Google remain notable strategic minority investors, reflecting capital commitments made before the listing rather than participation as sellers in this all-primary IPO.
Nomura, as cited by CNBC, said Jio’s capital-expenditure cycle was largely complete and expected free cash flow to improve sharply. The brokerage assigned a buy rating and a ₹1,340 target price, a forecast rather than a verified outcome. Jio traded above that target at the time CNBC reported the ₹1,360 price, illustrating how quickly a target based on the IPO price can be overtaken by first-day market trading.
CNBC also reported the view of Deven Choksey of DRChoksey FinServ that some investors who acquired stakes around 2021 may seek to sell after about six months, potentially when Jio could enter MSCI and Nifty 50 indexes. That is an analyst’s expectation, not a confirmed timetable for sales or index inclusion. For now, the confirmed markers are the ₹1,119 issue price, the ₹302 billion capital raise, and the ₹12.5 trillion market capitalization reported during Jio’s first trading session.