
Getty Images is reported to have entered Chapter 11 with a restructuring framework that would cancel all existing common shares, shift ownership of the reorganized company to its majority shareholders and reshape more than $2 billion of reported debt. The proposed transaction also calls for roughly $533 million of support from those shareholders, combining debtor-in-possession financing, a cash equity investment and the conversion of certain prepetition debt into equity.
The reported filing puts a formal restructuring process behind a plan Getty disclosed to investors on Oct. 12. Artforum reported two days later that the Seattle-based visual-content company was filing for Chapter 11. Getty’s securities filing described a prepackaged process and required the company to begin Chapter 11 cases by Oct. 21, subject to conditions and possible extensions. The company’s formal filing date could not be independently confirmed from a bankruptcy-court petition.
The transaction is consequential for three groups with sharply different outcomes: current shareholders would receive nothing, unsecured-note holders are slated for a collective cash payment, and majority shareholders would emerge with the company. It also follows a warrant dispute that produced a court-ordered judgment, a standstill agreement and an additional liquidity demand on a company already carrying substantial borrowings.
How Getty’s proposed restructuring allocates value
Getty’s Oct. 12 restructuring support agreement set out the mechanics of a recapitalization supported by majority shareholders and specified creditor groups. It contemplated approximately $533 million in total backing. That figure is not simply new cash for operations: it includes financing to fund the bankruptcy process, a cash equity investment and debt that would be exchanged for new equity.
The term sheet says existing equity interests, including Getty Images Holdings common stock, would be cancelled without any distribution. Majority shareholders would own all of the reorganized company, although a management incentive plan would dilute that stake. Such an outcome is consistent with a restructuring in which lenders and controlling owners supply the capital needed to preserve operations while public equity is deemed out of the money.
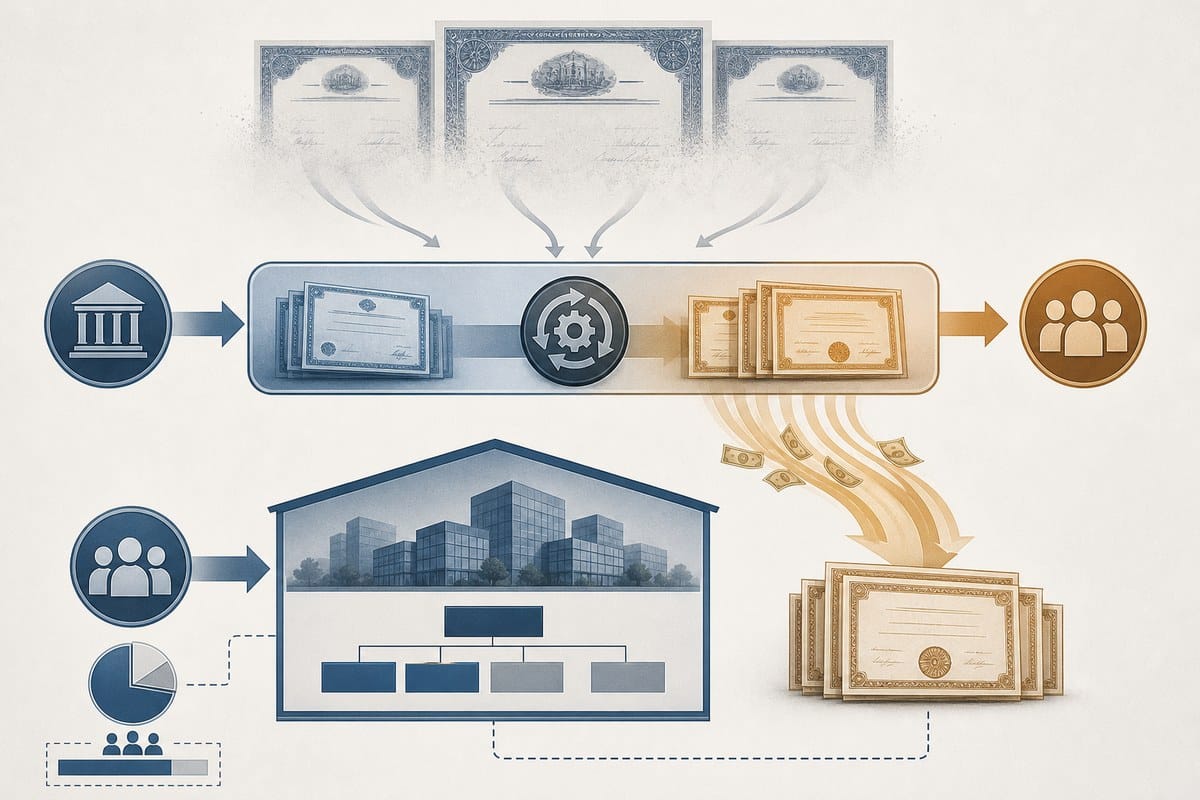
Holders of Getty’s unsecured notes would receive aggregate cash consideration of about $170.2 million under the proposed plan. The disclosure does not establish a final recovery percentage for every individual holder because the outcome remains subject to voting, court approval and other conditions. It does, however, show that the plan differentiates between unsecured creditors receiving cash and shareholders receiving no distribution.
Getty’s agreement was structured as a prepackaged Chapter 11 plan, a route companies use to negotiate key terms before seeking court approval. The approach can shorten a case relative to a conventional bankruptcy, but it does not make the plan final. Financing, creditor support, required approvals and bankruptcy-court confirmation remain material steps.
Warrant judgment added pressure to a leveraged balance sheet
The bankruptcy preparations came after litigation involving former warrant holders. In a separate Getty securities filing, the company said a New York court on July 27 ordered the clerk to enter judgment against Getty in favor of the plaintiffs. As of Aug. 25, the plaintiffs calculated the judgment, including interest, at approximately $92.3 million.
Getty appealed the relevant orders and reached a standstill agreement with the plaintiffs. As part of that arrangement, the company agreed to make an approximately $4.15 million partial payment, credited against the judgment. The filing records the company’s legal position and the plaintiffs’ judgment calculation; it does not establish that the litigation by itself caused the Chapter 11 process.
The financial scale helps explain why the dispute was important even if it was not the sole driver. At June 30, Getty reported $51.6 million of cash and cash equivalents, $702.1 million of short-term debt and $1.33 billion of long-term debt in its second-quarter filing. Combined debt was therefore about $2.03 billion, nearly 39 times its reported cash balance. The $92.3 million judgment calculation was roughly 1.8 times that cash balance.
Getty also reported $99.5 million in litigation reserves at quarter-end. That reserve exceeded the plaintiffs’ stated judgment calculation, but a reserve is an accounting estimate rather than cash set aside for one specific claim. Nor do June 30 figures show the company’s liquidity immediately before the reported Chapter 11 filing. They do show a balance sheet with limited cash relative to debt and potentially significant legal obligations.
A short path from court order to restructuring plan
The sequence unfolded quickly. The July court order was followed in August by the disclosed standstill and partial payment. In September, Octus reported, citing unnamed sources, that Getty was preparing a Chapter 11 filing amid a liquidity crunch, leverage and litigation-related payment obligations. The company then disclosed its restructuring support agreement on Oct. 12, with a stated deadline to commence Chapter 11 cases no later than Oct. 21.
Getty’s prior disclosures leave open the extent to which each pressure contributed to the filing. The warrant litigation had an identifiable judgment amount and payment requirement; the restructuring agreement addresses a broader capital structure, including creditor treatment, new financing and ownership. That breadth indicates the proposed case was designed as a company-wide recapitalization rather than a settlement mechanism for a single lawsuit.
The immediate practical issue is whether Getty can obtain the approvals needed to implement the prepackaged plan on the proposed terms. For holders of the company’s common stock, the disclosed answer is already clear: the agreement contemplates cancellation of their interests without a distribution.