
The Bank of Israel said cryptocurrency cannot be used to circumvent sanctions, publicly pushing back on Prime Minister Benjamin Netanyahu’s discussion of financial contingencies should Israel face banking or economic restrictions. The position, reported Oct. 24 by Ynetnews and corroborated by Anadolu Agency, places Israel’s access to international financial institutions and trading partners at the center of a political debate over digital assets.
Netanyahu had raised the prospect of preparations for possible sanctions in televised comments a day earlier, with cryptocurrency discussed as one potential option. There is no indication in the reports that sanctions are imminent or certain. But the central bank’s response addresses a practical constraint for an export-oriented economy: moving value on a blockchain is different from preserving access to correspondent banks, payment networks, suppliers, insurers, investors and customers that must comply with applicable restrictions.
What the Bank of Israel rejected
The reported central-bank message was not a broad rejection of digital assets. Its narrower point was that crypto cannot provide a route around sanctions, while Israel should work to avert sanctions and protect economic relationships with its principal trading partners. The published accounts did not link to a Bank of Israel release or a complete transcript of Netanyahu’s interview, so they do not establish the full wording or scope of the exchange. Still, multiple outlets reported the same core position, including The Media Line and The Jewish Chronicle.
Netanyahu later said he had heard objections, including advice from the Bank of Israel, but would decide what he considered appropriate. In follow-up comments reported by Jewish Insider, he characterized cryptocurrency as one possible means rather than a settled or exclusive policy. That clarification narrows the immediate policy claim: the dispute is not over whether Israel will replace its financial system with crypto, but over whether digital assets belong in contingency planning for a sanctions scenario.
The distinction has consequences for businesses evaluating the episode. A government can encourage a payment technology, but it cannot unilaterally recreate the network of legal permissions and private-sector relationships that supports cross-border commerce. The bank’s intervention effectively emphasized that preventing restrictions and sustaining foreign economic ties would be more consequential than identifying an alternative channel for transferring funds.
Why blockchain transfers do not restore commercial access
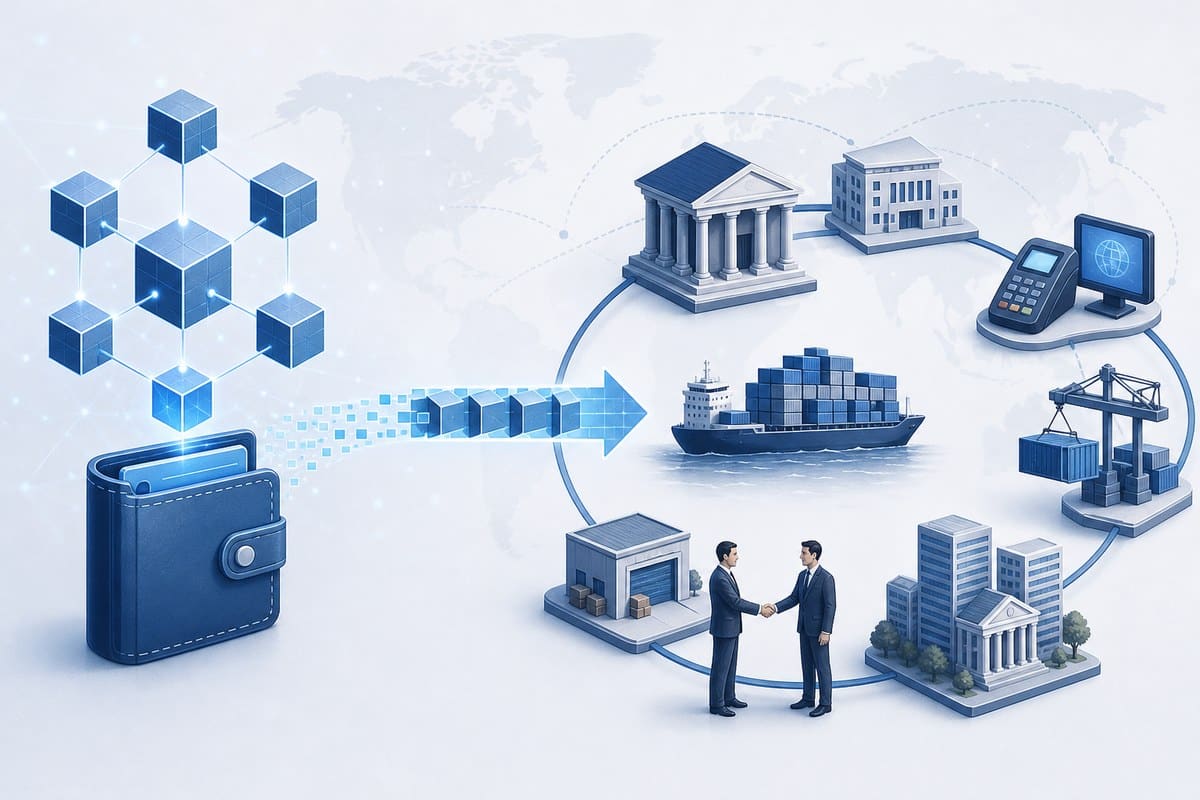
A blockchain can record and settle transfers between digital wallets without using a conventional bank for that specific transaction. It does not, however, make a prohibited transaction permissible or remove the need for conventional financial services across a wider commercial chain. Companies still need counterparties willing and able to sell goods, provide shipping, extend trade credit, insure cargo, convert currencies and receive payment under their own compliance rules.
Yair Avidan, a former Bank of Israel supervisor of banks, told Ynetnews that tokens and blockchain infrastructure do not erase legal prohibitions or sanctions obligations. Tomer Sharoni, chief executive of crypto-intelligence company Adresable, made a related point: digital-asset activity can be traced, and changing the payment rail does not alter the legal status of the underlying transaction.
That operational reality is especially relevant to the claim that cryptocurrency can function as an economic fallback. Crypto may transfer a unit of value, but it does not by itself supply the foreign-exchange liquidity, credit intermediation, regulatory approvals or trusted counterparties that businesses use in ordinary international trade. It also does not compel a bank, supplier or investor to maintain a relationship if doing so could expose that party to compliance or legal risk.
Critics cited by Ynetnews warned that trying to build an alternative crypto-based economy could weaken Israel’s access to banking, trade and investment, with possible pressure on capital flows, the currency and prices. Those are forecasts rather than established outcomes, and the reports do not show that the government has adopted such a strategy. They nevertheless explain why the Bank of Israel framed the issue around preserving existing links rather than testing their substitutes.
Questions remain over any government plan
The accounts leave an important factual gap: whether a formal government crypto contingency project exists. Netanyahu was reported as saying he had directed preparations, yet Ynetnews said officials in economic ministries and senior figures in the Prime Minister’s Office were unaware of the initiative he described. That is a significant but single-outlet report, not proof that no instruction was issued. It remains unclear whether any order was formalized, which agency would carry it out, or whether planning advanced beyond discussion.
The sequence is clearer than the planning details. Netanyahu’s comments on Oct. 23 triggered the debate; the Bank of Israel’s response followed on Oct. 24; and Netanyahu then said he had considered the objections while retaining decision-making authority. Follow-up reporting on Oct. 25 broadened the economic concern. Jewish Insider reported that more than 100 senior Israeli economic figures signed a letter warning that sanctions would severely damage Israel’s economic model.
For Israeli companies and foreign counterparties, the immediate signal is less about the usability of a particular token than about institutional priorities. The central bank’s reported position favors maintaining the financial and commercial relationships that crypto cannot independently reproduce, while the government has yet to clarify whether its contingency discussion has become an organized policy program.