
Advanced Micro Devices briefly surpassed a $1 trillion market capitalization for the first time on Sept. 21, joining Nvidia, Broadcom and Micron in a small group of U.S. chipmakers to clear the threshold. The intraday milestone came as AMD shares reached a record high during a broader advance in semiconductor stocks.
The move matters less as a permanent measure of AMD’s value than as an indication of what investors are now willing to pay for a company trying to become a fuller supplier of AI-computing infrastructure. CNBC reported that the stock rose 10% on the day and roughly 25% over a five-session winning streak. Separate Reuters reporting put the late-session gain at about 9% to 9.6%, while also describing gains in Intel, Qualcomm and the broader chip sector.
An intraday threshold, not a fixed valuation
Market capitalization is calculated by multiplying a company’s share price by its outstanding shares. It therefore changes continually during a trading day, and AMD’s crossing should be read as an intraday event rather than evidence that it closed above $1 trillion. A modest change in the share price can move a company back below a round-number valuation threshold, particularly after a sharp rally.
The available accounts agree that AMD reached a record intraday price and briefly topped $1 trillion, but they differ on the precise high. CNBC cited one figure, while Reuters reports published by The Globe and Mail cited another. The discrepancy may reflect differing market-data feeds or the moment each outlet measured trading. Neither account changes the principal fact: the company crossed the valuation mark during the session.
That distinction is relevant because market-cap milestones tend to attract attention disproportionate to their mechanical nature. In AMD’s case, however, the valuation followed a sustained move rather than a one-minute spike. Reuters said the shares had climbed more than 26% since an earnings-related selloff earlier in the month. CNBC put AMD’s year-to-date gain at more than 180%, with the exact figure naturally dependent on the trading time used for the calculation.
Data-center growth supplies the operating backdrop
Investors’ AI thesis rests partly on reported operating growth. AMD recorded second-quarter revenue of $11.54 billion, up 50% from a year earlier, according to CNBC. Its Data Center segment generated $6.7 billion, a 107% increase. Those numbers do not by themselves explain a single day’s share-price movement, but they show the business line that has become central to the company’s valuation case.
The company sells central processing units used in servers as well as graphics processors and other products aimed at AI workloads. Reuters reported that demand for CPUs paired with GPUs in inference servers has helped AMD take server share from Intel. Inference, the stage in which a trained model produces answers or other outputs, can require a mix of accelerators, conventional processors, memory and networking rather than GPUs alone.
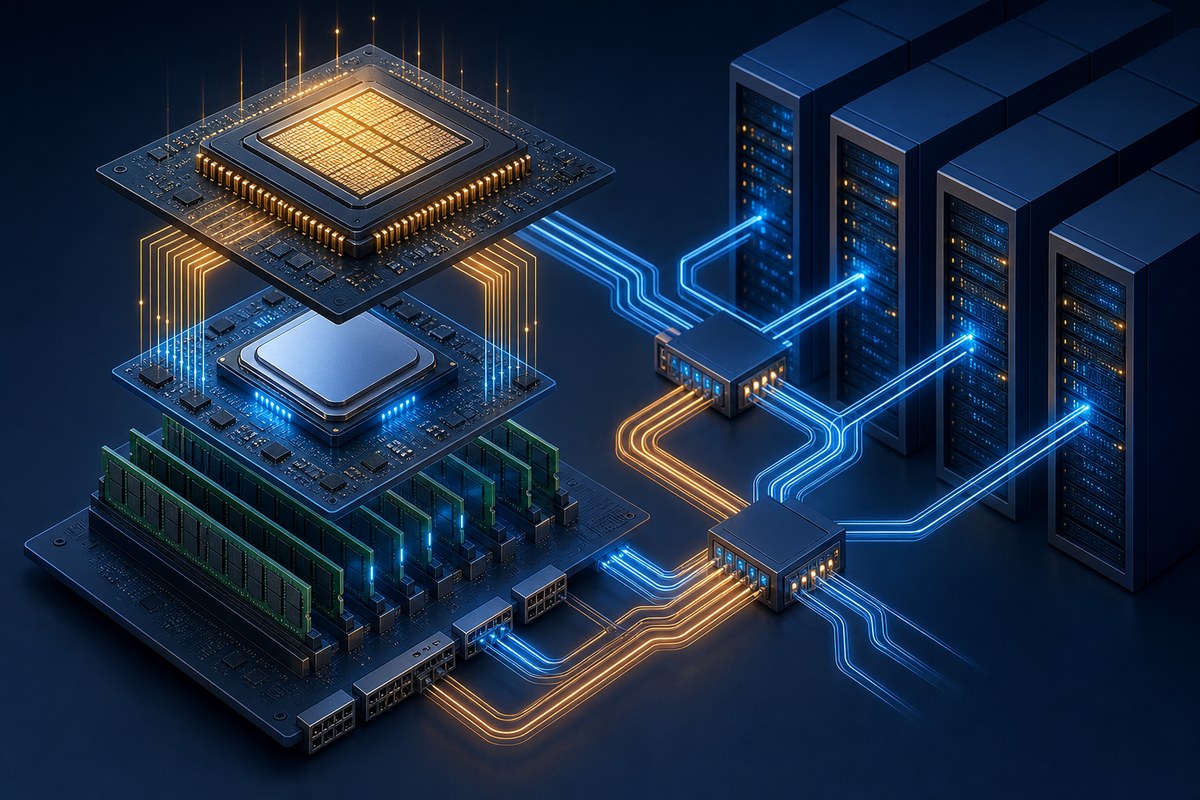
AMD is also attempting to compete on the design of a larger system. Reuters described the company’s push to offer processors, networking equipment and related hardware in more integrated configurations, positioning it more directly against Nvidia’s systems approach. That strategy may widen AMD’s addressable opportunity, but it also requires execution across product development, supply, software and customer deployment—not merely the sale of a standalone chip.
Targets point to a larger ambition, with execution still ahead
AMD had already set an aggressive strategic framework before the latest market move. At its November 2025 Financial Analyst Day, the company said it was targeting companywide revenue growth exceeding 35% annually over the next three to five years and data-center revenue growth above 60% annually over that span. The AMD investor release presented those figures as forward-looking objectives, not achieved results, and included the usual risks surrounding demand, competition and execution.
CEO Lisa Su has also said AMD expects to double data-center sales in 2027, CNBC reported. Such guidance helps explain why investors have assigned greater value to AMD’s AI position, but it should not be conflated with the company’s current revenue. The second-quarter figures are reported results; the multiyear growth goals and 2027 expectation remain management forecasts.
AMD’s $1 trillion crossing also puts its competitive position in perspective. Reuters described the company as the fourth U.S. chipmaker to reach that level, behind Nvidia, Broadcom and Micron. Yet Nvidia’s market value was reported at more than $5 trillion, leaving a substantial gap between AMD’s new valuation tier and the market leader whose AI accelerators remain the industry’s benchmark.
The sectorwide backdrop helped lift the shares on Sept. 21: Reuters said the semiconductor index rose about 2.6% to 2.7%, alongside gains in other large chip companies. AMD’s milestone was therefore both company-specific and part of a wider repricing of AI-linked hardware demand. Whether it can hold a $1 trillion valuation will depend on results that convert its data-center ambitions into durable sales and profits while competition in AI systems broadens.