A rental property can be profitable on paper and still leave its owner unable to pay the next large bill.
The problem is timing. Rent normally arrives once a month. Property taxes, insurance renewals, vacancies, legal expenses and repairs do not politely coordinate with that schedule. A water heater fails when it fails. A roof does not wait for the reserve account to recover.
- Profit, equity and liquidity are three different things
- Build reserves around risks, not round numbers
- Calculate debt coverage before adding debt
- Decide what the capital will accomplish
- Compare the main ways to access capital
- Model the ugly months, not the average month
- Protect the first property from the next deal
- Ask the lender questions that affect the business plan
- Run the rental like the small business it is
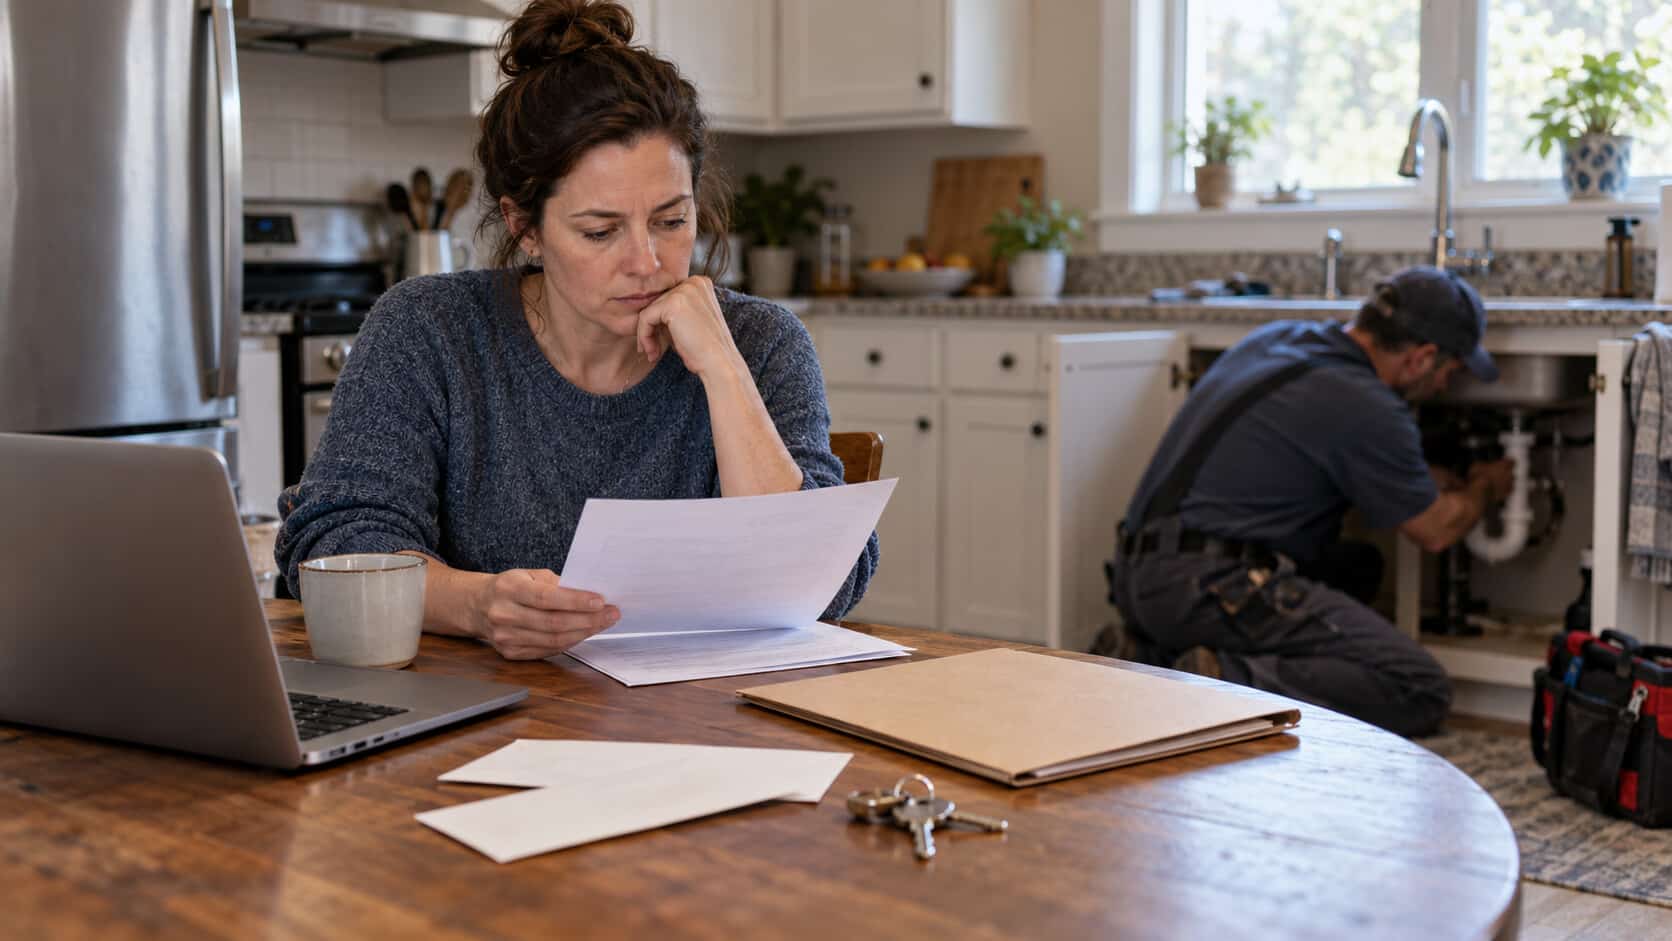
Large operators employ finance teams to manage liquidity. A person with one, two or five rentals often handles the same problem between tenant calls and a full-time job.
Small landlords therefore need to manage each property as a business. That starts with understanding the difference between profit, equity and cash.
Profit, equity and liquidity are three different things
Profit is what remains after income and expenses over a period of time. Equity is the property’s value minus debt secured by it. Liquidity is money that can be used now.
An owner might have $250,000 of equity in a rental and only $8,000 in cash reserves. If a vacancy, HVAC replacement and insurance deductible arrive together, the property may face a cash shortage despite being valuable and normally profitable.
This is not necessarily evidence that the investment is bad. It may mean the capital structure is brittle.
The first defense is a reserve account. Borrowing should not replace routine saving. Credit is useful for uneven or exceptional expenses, but using debt every month to cover ordinary operating costs is a warning that rent, expenses or leverage must change.
Build reserves around risks, not round numbers
Advice such as “keep three months of expenses” is easy to remember but may not fit the property.
A newer condominium with an association responsible for exterior maintenance has a different risk profile from a 70-year-old single-family home with an aging roof and private sewer line. A property in a hurricane-prone area faces different insurance and repair risks from one in a milder climate.
A more useful reserve plan includes separate estimates for:
- Mortgage payments, taxes, insurance and association dues during a vacancy
- The insurance deductible for the most plausible major claim
- Replacement of the most expensive aging system
- Turnover costs between tenants
- Legal, licensing and safety-compliance expenses
- Urgent travel or management costs for an out-of-state owner
- A buffer for slower rent collection or an unplanned rent concession
The reserve does not need to cover every disaster imaginable. It should cover the property’s most likely cluster of problems without forcing an immediate sale or high-cost loan.
Calculate debt coverage before adding debt
Debt service coverage ratio, or DSCR, compares property cash flow with debt payments. In plain language, it asks whether the property generates enough income to cover its financing obligations.
The exact formula can vary by lender and property type. Fannie Mae’s multifamily guidance, for example, defines a version of DSCR using net cash flow divided by debt-service payments. Small residential investment programs may instead use qualifying monthly rent divided by the property’s monthly housing expense.
Consider a simplified example:
- Qualifying monthly rent: $2,400
- Monthly principal, interest, taxes, insurance and association dues: $2,000
- Simplified DSCR: $2,400 ÷ $2,000 = 1.20
A ratio above 1.00 indicates that the counted rent exceeds the counted housing payment. A ratio below 1.00 indicates a shortfall under that calculation.
That number is useful, but it is not the property’s complete financial story. It may not fully capture maintenance, management, capital improvements, utilities paid by the owner or the cost of vacancy. An investor should calculate both the lender’s DSCR and a more conservative internal cash-flow figure.
Decide what the capital will accomplish
Borrowing makes more sense when the use of funds has a defined purpose and a plausible repayment path.
Common examples include:
- Replacing a failing system before it causes more expensive damage
- Completing a necessary turnover between tenants
- Adding a legal bedroom or accessory dwelling unit where permitted
- Improving energy efficiency to lower operating expenses
- Addressing safety or code requirements
- Funding a renovation that can support higher market rent
- Providing short-term liquidity between acquisition, repair and long-term financing
“I want cash available for deals” is not yet a plan. The investor should identify the expected use, maximum draw, repayment source and deadline.
The stricter rule is simple: do not use long-term property equity to conceal a permanently unprofitable operation. If rent cannot support normal expenses and prudent reserves, another loan usually postpones the reckoning.
Compare the main ways to access capital
Small landlords have several possible funding sources, each with different trade-offs.
- Cash reserves
Cash has no interest cost and creates no new lien. Its drawback is that using too much can leave the property exposed to the next emergency.
- Business or personal credit
A business line, credit card or personal loan may be faster and may avoid placing another lien on real estate. The available amount may be smaller, and unsecured borrowing can be expensive.
- Cash-out refinancing
A cash-out refinance replaces an existing mortgage with a larger new loan and provides part of the difference in cash. It can produce a substantial lump sum, but refinancing the full balance may be unattractive if the current mortgage has favorable terms.
- A HELOC
A home equity line of credit is revolving debt secured by property. An investor who wants to use one should first understand how a HELOC works, including the draw period, repayment period, variable-rate risk and fees.
The Consumer Financial Protection Bureau warns that a lender may freeze additional draws if property value falls significantly or if the borrower’s financial circumstances change. An unused credit line should therefore not be treated as identical to cash in the bank.
- A DSCR-based HELOC
Conventional underwriting often emphasizes the borrower’s personal income and debt-to-income ratio. That can be awkward for an investor whose tax return includes depreciation, business deductions or income from several properties.
Some programs instead evaluate the rental property’s income relative to its housing obligations. An investor comparing those options may consider a DSCR HELOC for real-estate investors, subject to the program’s credit, equity, property, reserve and underwriting requirements.
This structure can align the financing analysis more closely with the asset producing the income. It does not make the debt self-paying. Tenants can leave, rents can fall and repairs can interrupt cash flow while loan payments continue.
Model the ugly months, not the average month
Annual averages smooth away the events that cause liquidity crises.
Assume a rental collects $30,000 a year and appears comfortably able to support its expenses. That average may hide one vacant month, a $7,000 repair and an annual insurance premium arriving during the same quarter.
Before opening or drawing from a credit line, model at least five scenarios:
- The property is vacant for two or three months.
- Rent falls when the lease renews.
- Insurance and property taxes increase together.
- A variable borrowing rate rises.
- The planned renovation does not increase rent as much as expected.
Then ask whether rent and reserves could still make every required payment. If the answer depends on immediately finding a tenant, completing work perfectly or selling at a higher price, the plan has too little margin for error.
Protect the first property from the next deal
Investors often use equity from one property to acquire or improve another. This can accelerate portfolio growth, but it also connects their risks.
If Property A secures the line used to repair Property B, a problem at Property B can threaten the equity in Property A. The investor should document which asset secures the debt, which asset is expected to repay it and what happens if the second project is delayed.
Useful guardrails include:
- A maximum draw per project
- A written repayment date and source
- Separate operating accounts for each property
- A reserve that remains untouched after closing
- A limit on how many projects may depend on the same credit line
- A rule against using the line for ordinary personal spending
These controls may feel conservative during a rising market. That is precisely when they are easiest to establish.
Ask the lender questions that affect the business plan
Before choosing a property-secured line, ask:
- How does this program calculate qualifying rent and DSCR?
- Which expenses are included in the debt calculation?
- Is personal income documentation required?
- What reserves must be documented?
- Which property types and ownership structures are eligible?
- Is the rate variable, fixed or convertible?
- How long is the draw period?
- What happens to the payment after that period?
- Are there annual, inactivity or early-closure fees?
- Is there a prepayment penalty?
- Can the line be reduced or frozen?
- What lien position will the loan occupy?
Compare written terms rather than product names. Two loans carrying the same label can differ materially in payment structure, fees and restrictions.
Run the rental like the small business it is
Rental equity is valuable, but equity alone does not pay an invoice. A resilient landlord keeps cash reserves, understands the property’s true coverage ratio and borrows only for a defined purpose with a realistic exit.
The goal is not to avoid debt at all costs. It is to prevent a short-term cash shortage from forcing a bad long-term decision.
A good property should produce income. A good financing plan should give that income enough time and room to do its job.